State Income Tax Withholding Rules for Remote Employees
Hiring remote workers in new states creates unexpected tax obligations beyond income withholding.
Idris Nakamura
Section
11 stories in Multi-State & Global Workforce.
Hiring remote workers in new states creates unexpected tax obligations beyond income withholding.
Misclassification triggers stacked liabilities across taxes, penalties, and retroactive benefits.
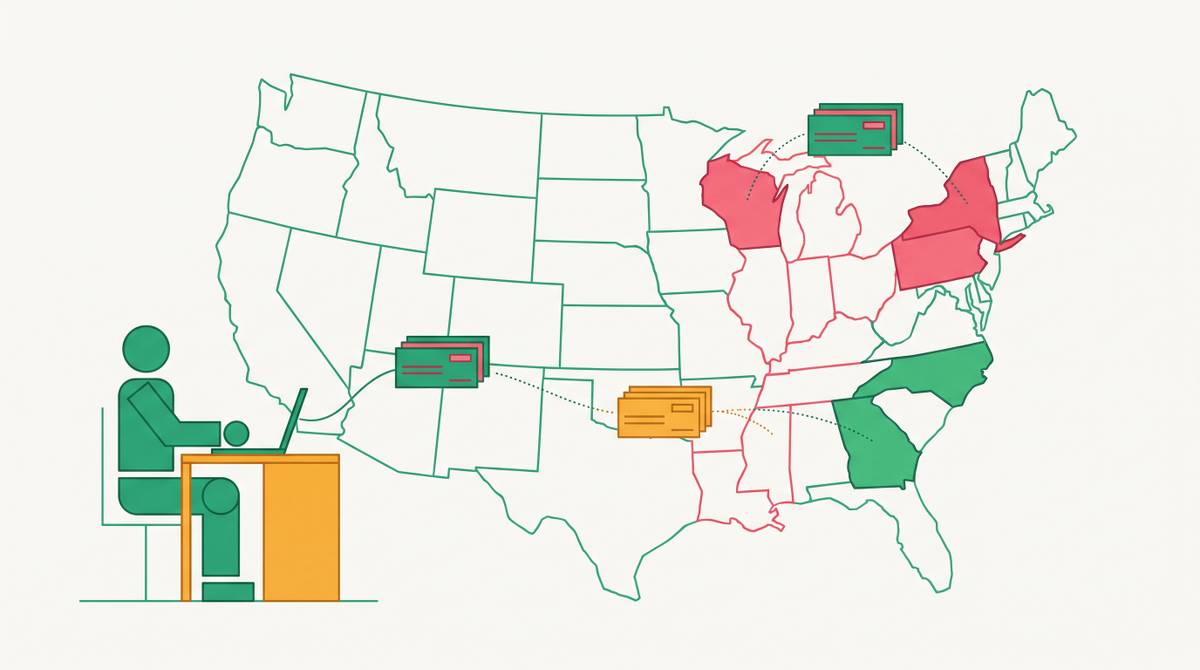
Each new state requires separate registrations, accounts, and deadlines simultaneously.
State laws, not federal rules, determine contractor classification and carry the steepest penalties.
One remote worker can trigger tax obligations in an entirely new state.
The 2024 DOL rule ditches shortcuts and uses six factors to determine employee status.
Courts weigh totality of evidence to distinguish employment from contractor status.
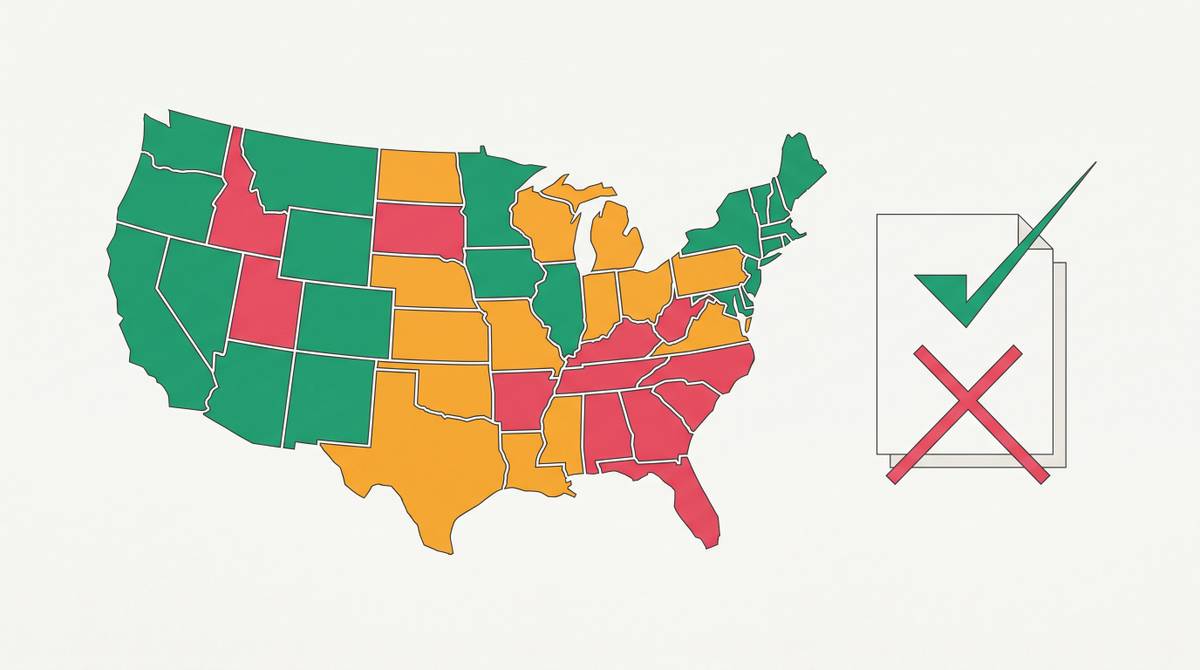
States tax income based on where work actually happens, not where employers claim it's temporary.
The $2,000 threshold applies only to 2026 payments, not 2025.
Hidden tax and labor obligations beyond payment processing create serious compliance risk.
Employers must deposit FUTA quarterly once liability hits $500, not annually on January 31.