Global Contractor Payment Compliance and Misclassification Risk
Misclassification triggers stacked liabilities across taxes, penalties, and retroactive benefits.
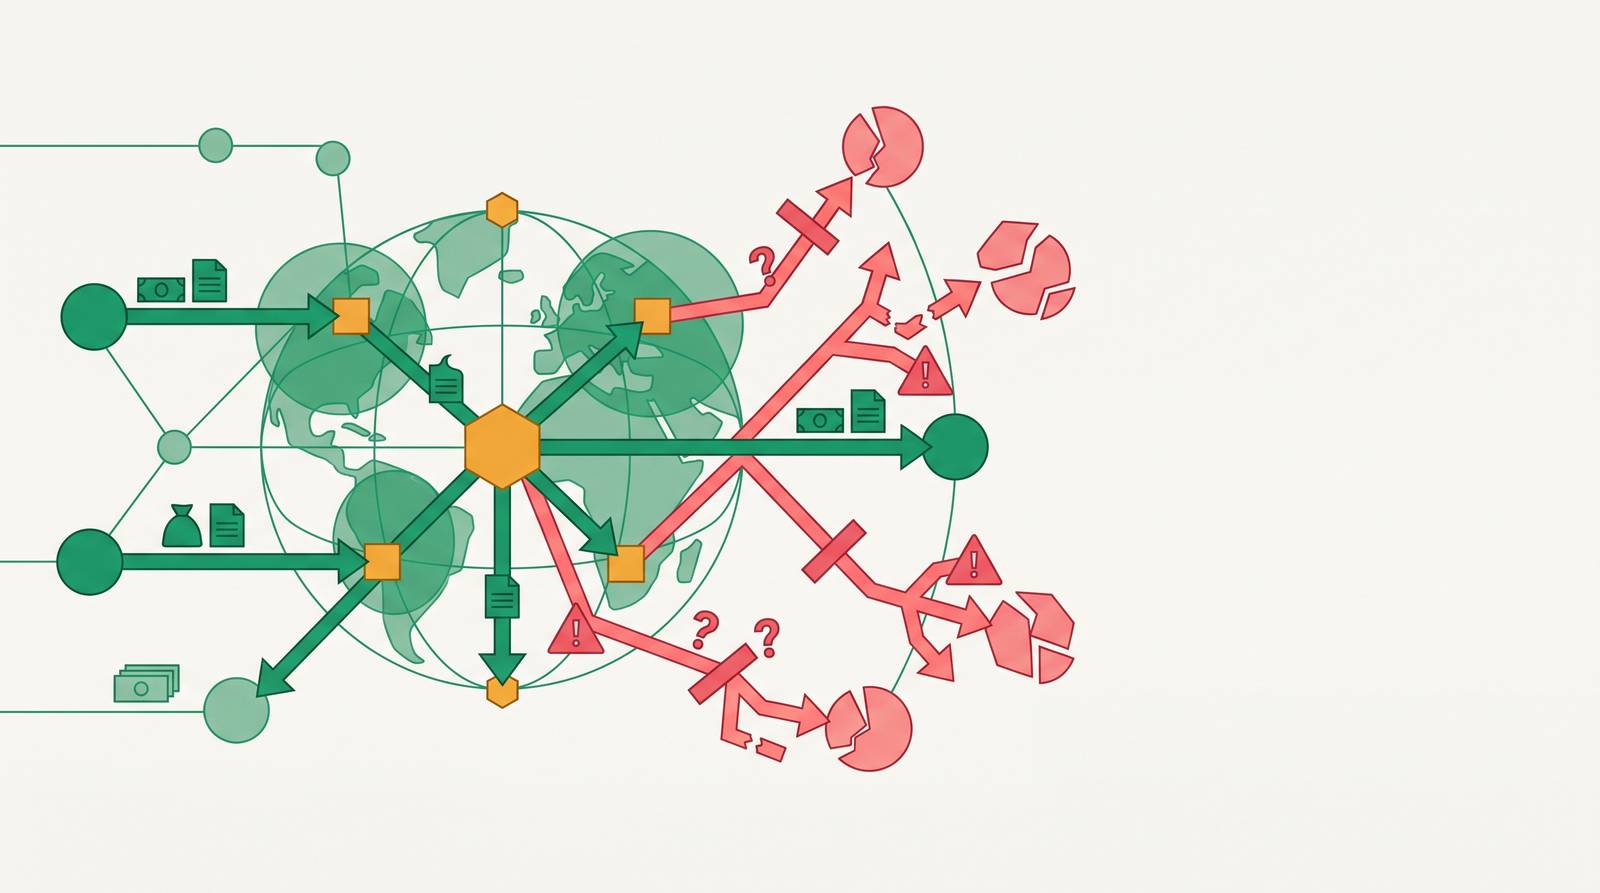
No international standard for contractor classification exists. This isn't a gap the legal community is quietly closing; it's a structural feature of global labor law, baked in by design. Each country has built its own legal tests from the ground up, shaped by distinct political pressures, labor protection philosophies, and tax collection priorities. The result is a matrix of frameworks that can produce directly contradictory conclusions about the same working arrangement.
The major classification tests a global company will encounter fall into several broad families. Behavioral control tests ask whether the company controls how the work is performed, not just what the outcome should be; this framework underlies IRS guidance in the United States and informs much of the UK's approach. Economic dependence tests focus on whether the worker is financially reliant on a single client, regardless of how the contract is written; Germany, France, Spain, and much of the EU weight this heavily. Substitution tests ask whether the contractor can send someone else to do the work, and both the UK and Australia apply versions of this criterion. Presumption-of-employment rules, increasingly common after 2024, flip the burden of proof entirely, assuming the worker is an employee until the company demonstrates otherwise.
These tests don't align, and understanding why matters. An engagement that passes the IRS three-factor analysis can simultaneously constitute an employment relationship under Germany's Scheinselbständigkeit doctrine or Brazil's economic dependence standard. Companies that build a single global classification framework on a U.S.-centric model are applying the wrong test in most of the jurisdictions they operate in.
The written contract matters, but in most jurisdictions it's insufficient. Courts and labor authorities look at the actual working relationship: who sets the schedule, how integrated the worker is into company operations, whether tools and equipment are provided, how economically dependent the worker has become. A contract that says "independent contractor" on its cover page doesn't resolve those questions. Brazil makes this especially explicit. Its enforcement authorities scrutinize exclusivity, work hours, and operational integration with a rigor that has produced severe penalties for foreign-paying companies that assumed a well-drafted services agreement would carry the compliance burden.
The divergence across these frameworks is widening rather than trending toward resolution. A company that treats classification as a one-time legal question rather than a jurisdiction-specific, ongoing analysis is building its contractor program on a premise that no labor authority will honor.
The wave of reclassification legislation that changed the enforcement landscape between 2024 and 2026
The compliance environment for global contractors isn't static, and the pace of change between 2024 and 2026 has been fast enough to strand companies operating on perfectly sound legal analysis from eighteen months prior. More than 30 countries updated their payroll, employment tax, or mandatory benefits frameworks during this period. The direction is consistent: enforcement is expanding, presumptions are shifting toward employment, and the burden of proof is falling on the company rather than the worker.
Four developments stand out.
The EU Platform Work Directive moved into active enforcement in 2025, introducing a presumption of employment for platform workers who meet certain activity thresholds. For companies operating in EU member states, this is a structural shift in how proof is allocated. Where the company previously needed to demonstrate that a worker was an employee, it now must demonstrate that a worker isn't. That inversion carries substantial operational consequences, and companies that haven't restructured their classification process accordingly are operating without a legal defense.
The Netherlands ended its enforcement moratorium on contractor arrangements in January 2025, without ambiguity or phase-in. Companies that haven't revisited their Dutch contractor arrangements since that date are operating on stale analysis in a jurisdiction that is now actively looking for exposure.
Australia's Closing Loopholes reforms, which took full effect in 2024, revised the statutory definition of employment and expanded the Fair Work Commission's authority to scrutinize contractor arrangements. Critically, the reforms clarified that the written contract no longer controls the classification outcome. Actual working conditions determine status. Professional services and technology companies, which had historically relied on contract language as a compliance foundation, are now among the most exposed.
Spain's enforcement record illustrates what aggressive application of these principles looks like. The Glovo ruling resulted in a fine of approximately €79 million for wrongly classifying delivery workers as self-employed. This wasn't a close legal question resolved against a marginal operator. It was a definitive judicial statement about how platform-style contractor arrangements are treated when workers meet the integration criteria under Spanish law.
Each of these developments shares a common enforcement posture: authorities are initiating audits rather than waiting for worker complaints. For companies that built their contractor model under an earlier, more tolerant regulatory environment, the arrangements themselves have not changed. Their legal status has.
What misclassification actually triggers (the full liability stack)
Misclassification is frequently described as a compliance risk. Accurate, but inadequate. A reclassification finding is a simultaneous, multi-dimensional financial event. It doesn't produce a single fine; it produces a stack of liabilities that arrive together, calculated retroactively for the full duration of the engagement.
A 2023 IRS audit report found that 38% of audited contractors were misclassified, representing an estimated multibillion-dollar loss in U.S. tax revenue alone. This is a systemic pattern present in more than a third of audited relationships, not an edge-case error made by unsophisticated operators.
The liability stack typically includes the following, simultaneously. Back payroll taxes cover the employer's share of contributions (FICA in the United States, National Insurance in the UK, or equivalent social contribution regimes elsewhere) calculated retroactively from the engagement's start. Penalties and interest accumulate on top of the underlying tax liability; in high-compliance jurisdictions, these additions can exceed the base amount. Benefit back-payment obligations apply in countries where employees are entitled to paid leave, health insurance, or pension contributions; a reclassified worker is entitled to all of it, retroactively. Statutory protections carry the same retroactive logic, including minimum wage top-ups, overtime, and termination rights. That last item is particularly consequential: a contractor relationship that ends after a reclassification finding can simultaneously become a wrongful dismissal claim.
Recent enforcement actions confirm that these liabilities are not theoretical. Uber and Lyft settled a Massachusetts misclassification case in June 2024 for a combined $175 million. Nike faces potential tax exposure exceeding $530 million across four jurisdictions simultaneously, a direct consequence of applying a uniform classification approach across markets with divergent legal standards. For a scaling company with 50 to 300 contractors, a single enforcement action in one jurisdiction can produce a liability that rivals or exceeds the entire annual cost of the contractor program it governs.
The payment mechanics that create compliance risk even when classification is correct
Classification and payment compliance are distinct obligations. A contractor relationship that passes every applicable legal test can still generate tax liability, regulatory exposure, and audit risk at the payment level. Companies that resolve classification correctly and treat payment as a mere execution detail are managing half the problem.
Tax withholding at source is the most commonly misunderstood payment-side obligation. Many countries require the paying company to withhold income tax or value-added tax equivalents directly from contractor payments, even for workers who are legitimately self-employed. Failure to withhold makes the payer liable for the unwithheld amount, regardless of whether the contractor subsequently pays their own taxes. The applicable rate varies by country, by payment type, and by whether the contractor is an individual or a legal entity.
Currency and payment channel requirements add a separate layer of execution risk. Several countries in Latin America, Africa, and Asia maintain currency controls or restrict how cross-border payments are received. Paying in U.S. dollars through a consumer transfer platform into one of these markets can create local tax reporting gaps or violate central bank regulations. Local bank account requirements and mandatory use of regulated payment rails are legal requirements, not administrative preferences, and violations can expose both the paying company and the receiving contractor to liability.
Invoice and documentation standards matter more than most finance teams realize. Many jurisdictions require contractors to issue a tax-compliant invoice, including registration numbers and correct VAT treatment, before payment is legally permissible. Paying without a compliant invoice can void the company's ability to deduct the expense and invite reclassification scrutiny from tax authorities reviewing the transaction. A missing VAT number on an invoice processed in 2023 is a fully intact audit exposure in 2026.
Permanent establishment risk is the most underappreciated payment-adjacent compliance issue. A contractor who has authority to sign contracts on the company's behalf, or who functions as a de facto sales representative in their home market, can inadvertently create a corporate tax presence in that country. PE status brings the company into scope for local corporate income tax and filing obligations. This risk goes undetected partly because it sits at the intersection of tax, legal, and operations rather than cleanly inside any one function, and partly because the triggering facts accumulate gradually as a contractor relationship evolves beyond its original scope. By the time someone notices, the exposure has typically been building for months.
The highest-risk jurisdictions and what makes them outliers
Enforcement risk is not evenly distributed across global contractor markets. A small number of jurisdictions account for a disproportionate share of enforcement actions, penalty severity, and structural complexity for foreign-paying companies.
Brazil applies strict economic dependence criteria across its labor courts. Enforcement authorities scrutinize exclusivity, the degree to which a worker is integrated into company operations, and consistency of work hours. Labor courts are structurally claimant-friendly, meaning that even companies that ultimately prevail in litigation incur meaningful defense costs and reputational exposure. Settlement doesn't necessarily resolve the matter, because class-style labor claims can follow from individual findings. Brazil is not a jurisdiction to approach with a template.
Germany's Scheinselbständigkeit doctrine treats economic dependency on a single client as a heavily weighted indicator of employment. The German tax authority applies this test rigorously. A contractor who derives the substantial majority of income from one company, regardless of what the contract says, is vulnerable to reclassification. The doctrine rewards nothing for good intentions or careful drafting.
The Netherlands moved from tolerance to active prosecution in January 2025. The legal standard didn't change when the moratorium ended; enforcement did. Companies that established contractor arrangements before that date and haven't revisited them are exposed in a jurisdiction that is now actively looking.
Spain's labor inspectorate operates across gig and professional services sectors, not only platform companies. The Glovo ruling established the doctrinal framework, and inspectors are applying it beyond the delivery context. Any arrangement where a contractor functions with sufficient operational integration into the client's business carries reclassification exposure.
The United Kingdom's IR35 off-payroll working rules place the tax determination obligation squarely on the client company for medium and large businesses. The company must assess whether a contractor would be an employee if engaged directly, and if the determination is that they would be, the company is responsible for the associated tax. That assessment must precede the engagement, not follow a dispute.
Australia's Closing Loopholes reforms make the written contract a starting point for analysis rather than a determinative document. The Fair Work Commission's expanded jurisdiction to hear reclassification disputes, including from contractors in professional services and technology roles, means that industries which previously considered themselves outside the platform-worker conversation are now squarely inside it.
None of these markets responds to template analysis. Each is a jurisdiction-specific compliance question requiring jurisdiction-specific expertise.
How fragmented contractor management creates compounding risk at scale
The typical contractor management architecture at a scaling company is a spreadsheet. Contractor names, payment amounts, wire transfer confirmations. Classification was assessed once at onboarding, perhaps using a general framework rather than a country-specific test. The invoice came in, the payment went out, and no one flagged the arrangement for review when the contractor's scope changed six months later. This pattern holds until it doesn't.
That architecture functions reasonably well at low contractor volumes in stable, low-enforcement markets. It breaks at scale, and it breaks across multiple dimensions at once.
Classification decisions go stale. A contractor hired for a discrete, time-limited project who has since become a regular operational resource has crossed the economic dependence threshold months before anyone noticed. The legal standard applied at onboarding was accurate for the original relationship; it describes nothing about the current one.
Law changes apply retroactively to existing arrangements. The Netherlands moratorium's end, Australia's definitional reform, the EU Platform Work Directive's enforcement shift: none of these applied only to new contractor relationships established after their effective dates. Companies monitoring their legal obligations only at the onboarding stage have no mechanism to detect when an existing arrangement's compliance status has changed because the governing law changed around it.
A 2024 PayrollOrg survey found that 30% of respondents named managing multiple vendors as a primary challenge in global payroll operations. Each vendor carries its own compliance logic, data format, and update cadence. Reconciling them across a growing contractor base is a manual function that doesn't scale proportionately; it scales faster than headcount does, because complexity compounds while staff capacity grows linearly.
Documentation gaps accumulate invisibly. An invoice missing a required tax registration number, a payment routed through an unregulated channel, a withholding calculation that applied last year's rate to this year's payment. Individually, each is manageable. Across 50 contractor relationships in 12 jurisdictions over three years, the aggregate creates an audit profile that is genuinely difficult to remediate retroactively. No single gap is catastrophic. The accumulation is what gets you.
The structural choices companies have for paying contractors compliantly (and what each one actually covers)
Three primary structural models exist for engaging and paying global contractors compliantly. They are not interchangeable. Each covers a different portion of the compliance obligation, and selecting among them requires honest assessment of jurisdiction risk, relationship structure, and contractor volume rather than a preference for the lowest-friction option.
Direct engagement with local compliance ownership
The company pays the contractor directly and retains full responsibility for classification analysis, withholding, invoicing standards, currency compliance, and PE monitoring. This model is appropriate in low-enforcement jurisdictions with stable legal frameworks, where the compliance obligations are well-understood and the company has the expertise to manage them.
The limitation is expertise cost. Direct engagement requires current, jurisdiction-specific legal or tax knowledge for every market where contractors are engaged. That is achievable for a small number of well-understood markets; it doesn't scale efficiently across a diverse global contractor base. As the number of markets grows, so does the cost of maintaining the expert coverage the model requires, and that cost tends to be underestimated until an enforcement action makes it concrete.
Contractor of Record
A Contractor of Record provider engages the contractor on the company's behalf through its own local or regional infrastructure. The CoR entity takes on employer-side compliance obligations, including classification management, withholding, and statutory contributions, and invoices the company a service fee. This model transfers the classification risk and payment-side obligations to the CoR provider.
The quality of protection this model provides is entirely a function of the provider's compliance infrastructure and the terms of its indemnification. A CoR arrangement with a provider that lacks genuine local legal presence in the relevant jurisdiction, or whose contract limits liability significantly, is a compliance transfer that won't hold under audit. Providers worth evaluating include Deel, Papaya Global, and Multiplier, among others. The critical evaluation criteria are depth of in-country legal infrastructure, coverage of the specific jurisdictions where the company operates, and the scope and limits of indemnification provisions. Read those provisions carefully. The gaps in them are where the risk lives.
Employer of Record
An EoR converts the contractor relationship into a formal local employment relationship through the EoR's legal entity. The worker becomes a local employee of the EoR company, and the engaging company pays a service fee covering employer costs and the EoR's margin. This model fully resolves classification risk, because contractor status is replaced with confirmed employee status.
EoR is the correct answer when the working relationship has substantively crossed the employment threshold and the company shouldn't be treating the worker as a contractor any longer. Continuing to pay as a contractor after that point is the misclassification. EoR services typically run from $199 to $599 per employee per month, depending on the jurisdiction and provider. That cost is real and should be weighed honestly, alongside the cost of the enforcement action it prevents.
There is rarely a single answer across a global contractor base, which is itself an argument for building the evaluation process into the engagement workflow rather than defaulting to habit.
What a proactive compliance process looks like operationally (before an audit, not after)
The companies that manage global contractor compliance effectively share one structural characteristic: they treat the classification decision as the beginning of an ongoing process, not a one-time gate. Compliance is built into engagement workflows before any contract is signed, and it includes monitoring mechanisms that persist through the life of the relationship.
Operationally, the process begins with country-specific classification analysis at engagement start. This means applying the legal test the relevant jurisdiction actually uses, not a U.S. framework generalized across markets. The analysis should be documented with care. Enforcement investigations routinely ask what process the company followed, not only what conclusion it reached. A documented, methodologically sound analysis that reached a wrong conclusion is in a materially better legal position than an undocumented correct one.
Ongoing monitoring requires defined review triggers. Any change in work scope, degree of exclusivity, relationship duration, or operational integration should prompt re-evaluation of classification status. The worker who was legitimately independent at month two isn't necessarily so at month fourteen. Law change monitoring is a separate, parallel obligation: when a jurisdiction updates its classification framework, existing arrangements in that market require fresh analysis, regardless of when they were established.
Payment compliance is a recurring function, not a setup task. Withholding rates change. Invoice requirements evolve. Currency controls are updated. Maintaining an accurate, current understanding of payment-side obligations requires the same monitoring infrastructure as classification, and the two should be managed together rather than by separate teams operating on separate update cadences.
The documentation practice matters independently of any classification outcome. Complete records, including the classification analysis, the contract, all invoices, all payment confirmations with applicable withholding documentation, and any subsequent re-evaluations, constitute the company's defense in an audit. That defense is assembled before the audit begins. By the time an enforcement authority requests documentation, the company that has maintained it consistently occupies a fundamentally different legal position from the one scrambling to reconstruct records under pressure.
Global contractor compliance is operationally demanding. It requires country-specific expertise, continuous monitoring, honest classification analysis, and rigorous payment documentation across a regulatory environment that is actively tightening. Get it right, and the cost is real but manageable. Get it wrong, and the jurisdictions covered in this piece will tell you exactly what that looks like.