Employer of Record vs Direct Entity for International Hiring
Explore when to use an employment intermediary versus building your own legal structure abroad.
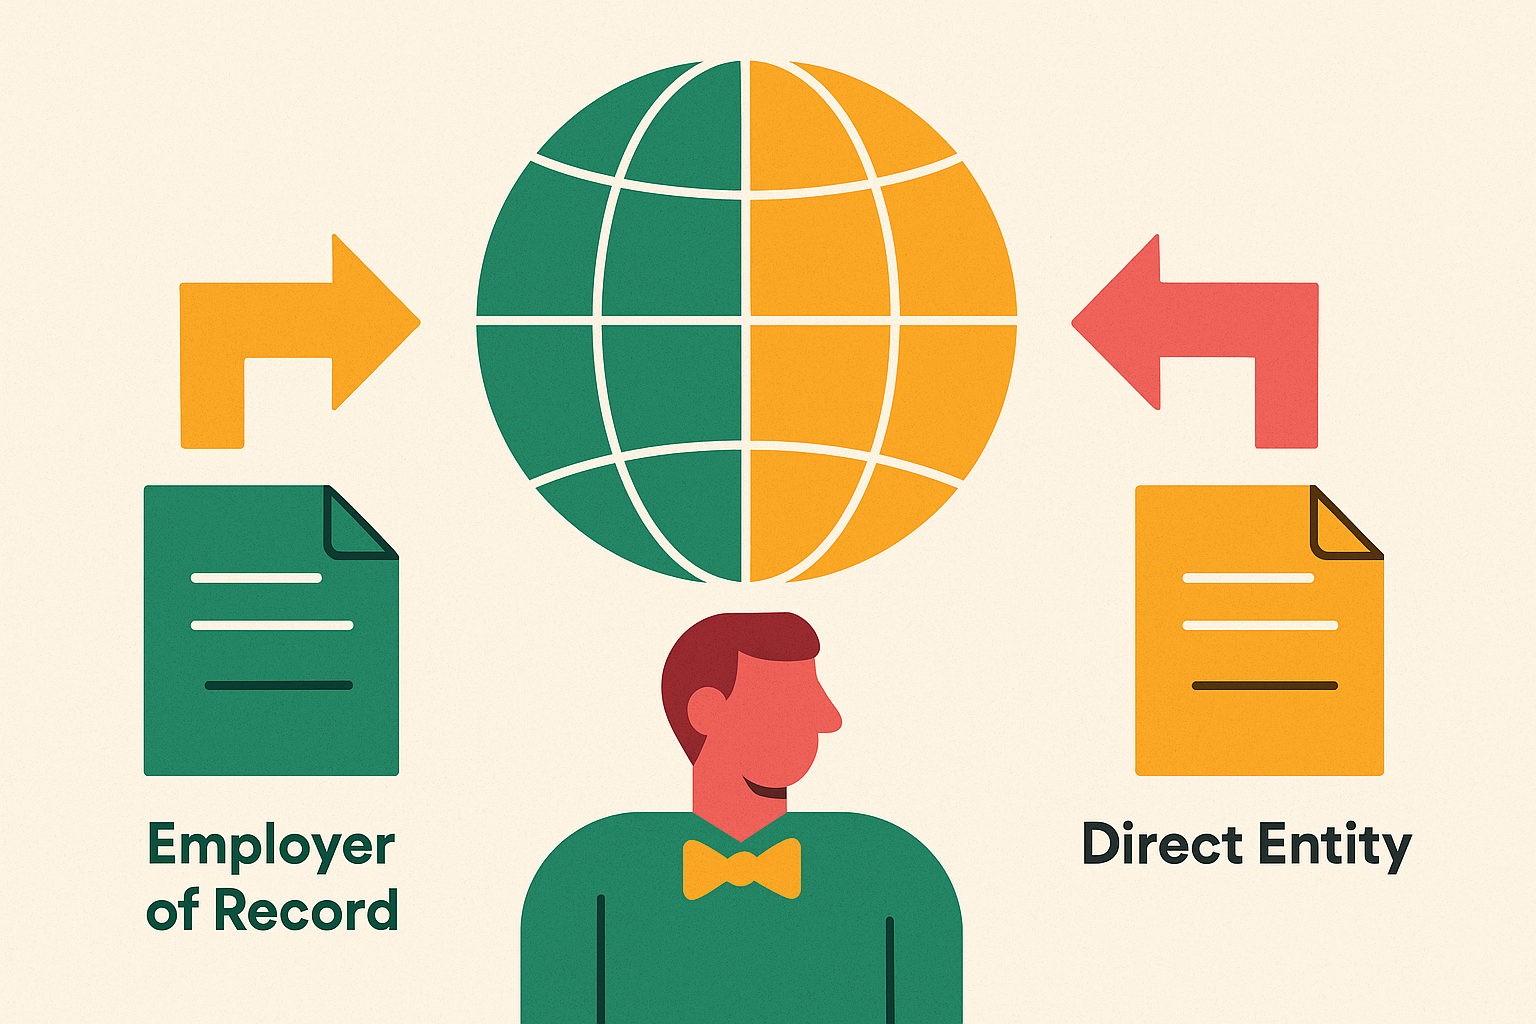
If you hire someone in another country, you need a legal employer presence there from day one. No compliant middle ground sits between using a third-party employment model and standing up a direct entity, and the companies that try to find one usually land in contractor misclassification instead. Legal direct employment abroad requires three things at once: a registered employer presence (a subsidiary, a branch, or a foreign employer registration), a payroll cycle that withholds income tax and social charges correctly under local rules, and an employment contract that meets the country's labor law, statutory benefits included. A worker who lacks any one of those three is not legally employed anywhere, no matter what the offer letter says. Treating "direct hire" as a shortcut, a way to put someone on staff informally without building the infrastructure behind it, misreads what the term requires: the company becomes the legal employer under local law, and that status demands months of setup, not a signature.
When a company skips this infrastructure, the default outcome is misclassification, which creates permanent establishment exposure along with back-tax liability that can surface years after the hire was made. An EOR exists to solve exactly this prerequisite problem. Papaya Global describes the model directly: an EOR hires the candidate on the client's behalf through its own local entity, handling payroll, taxes, and statutory benefits, while the hiring company keeps day-to-day management of the person's work. The choice was never EOR versus contractor, because you could never legally use the contractor route for work that functions like employment. It is EOR versus entity, and each path carries real costs that compound on a different schedule as headcount grows.
What an EOR owns
An EOR is the legal employer on paper. But in every sense that affects how the work gets done day to day, the client company is still the operational employer. The EOR owns the employment contract itself, drafts it, processes payroll and withholds tax, administers statutory benefits, sets notice periods and severance formulas according to local law, and files with the relevant labor authorities. The client company keeps everything connected to managing the person: performance decisions, project direction, feedback, and the call on when someone gets terminated, even though the EOR carries out the legal mechanics of that termination once the decision is made.
In practice, this split means the worker reports to a manager inside the client company, uses the client's tools, and operates inside the client's culture, and never interacts with the EOR directly. So the model scales without disrupting how teams function, because you never see the EOR in daily work. The split starts to matter in a few specific places once a company is relying on it at any real scale. Benefits design is one: the EOR controls the structure of what's offered, and the client has limited room to customize beyond that structure. IP assignment language is another: the EOR drafts the contract, and the client reviews and signs off on the wording rather than writing it from scratch. Data-processing terms carry the same constraint, because an intermediary sits inside the employment chain between the company and the worker. That arrangement constrains how much the client can negotiate on data-handling terms, and it becomes a real friction point if the company later moves that employee onto a direct entity and finds the EOR's contract language doesn't match its own security posture or infrastructure requirements.
The cost structure of each model
EOR and direct entity follow two different cost shapes, and which one wins depends on how many people a company employs in a given country, not on which model sounds more modern or more controlled. EOR costs scale linearly with headcount. Each employee carries a monthly fee, a flat charge or a percentage of payroll depending on the provider, on top of that worker's local salary and statutory benefits. Deel's pricing breakdown notes that the fee itself varies by country because administrative complexity and benefits overhead differ sharply from one market to the next: Germany, for instance, carries more benefit-program administration than many other countries, and that complexity raises the fee directly. Providers also differ on FX policy, deposit requirements, and payroll pre-funding, so if you compare two EOR quotes without requesting all-in fee documentation in writing, you're comparing incomplete numbers.
Direct entity costs run in the opposite direction. Registering an entity means legal fees, local director requirements, and filing fees up front, and the ongoing compliance overhead (a local payroll team or an outsourced payroll provider, annual filings, country-specific reporting) stays largely fixed whether the entity employs five people or fifty. That fixed-cost shape is the entire logic of the break-even calculation. Below a sustained headcount threshold in a given country, the EOR's per-seat fee costs less than spreading an entity's fixed overhead across a small team. But once you cross that threshold, the fixed costs dilute across enough employees that the entity's per-seat cost drops below what the EOR charges per head. Entity costs only clearly win out once a company reaches a sustained, large in-country presence, the kind that justifies a long-term market commitment and, in some cases, physical office space.
The crossover point itself is not a single number a company can apply everywhere. It shifts by country based on entity setup cost, the complexity of local payroll, and what the EOR charges in that specific market, so the calculation has to run per country rather than as a global average. The cost structure diverges so sharply that the inflection point often arrives sooner than a company expects, especially in jurisdictions where EOR fees run high relative to what a fixed-cost entity would require there. Two situations push a company toward direct employment even before headcount reaches that crossover. Senior hires with equity compensation are one, because cross-border equity taxation gets harder to administer through an EOR intermediary. High-protection jurisdictions with intricate termination procedures are the other, and there a direct employment relationship gives the company clearer procedural footing than a third party would.
Stage 1: Using EOR to enter a market fast and test before committing
For a company's first hire, or its first handful of hires, in a new country, an EOR is the right default. It's the right default because the alternative, standing up an entity, takes months and locks the company into commitments it isn't ready to make yet. Speed is what makes the early-stage case. G-P's platform overview notes that EOR onboarding takes days rather than months, because the EOR's local entity already exists, while entity registration can run weeks to months depending on the jurisdiction. Papaya Global frames the advantage the same way: an EOR lets a company hire ahead of its own infrastructure, putting someone on the ground and productive before the legal and operational groundwork is finished.
That speed serves a specific purpose beyond convenience: it lets a company test a market before committing to it. An EOR makes it possible to find out whether a country actually has the talent density, the customer demand, or the operational fit a company is betting on, without locking in the fixed costs of a permanent entity first. If the market doesn't work out, the company exits without the burden of winding down a legal entity it just built. Deel's analysis points out a related advantage for project work: EOR arrangements don't require long-term commitment, and month-to-month contracts are available, which fits projects with a defined end date far better than entity formation would. A similar logic applies after an acquisition. A company absorbing a team abroad can run that team through an EOR for a transition period, buying time to integrate payroll and HR systems without disrupting people who just joined through the deal. That's a bridge arrangement. In every one of these cases, the EOR also closes off a risk many early-stage companies take on without realizing it: when a role looks like full-time employment, with one client and direct day-to-day management, treating that person as a contractor invites exactly the misclassification exposure the EOR exists to prevent.
Stage 2: When growing headcount in one country makes a direct entity worth modeling
You don't need a specific headcount number to know a direct entity deserves serious modeling. It's sustained, growing headcount in one country paired with a long-term commitment to that market and a genuine need for full control over the employment relationship. The fixed-cost logic from earlier runs in the company's favor once it crosses that point: a separate entity, a local director, and local filings all carry their own setup and ongoing overhead, but once those costs are in place, each additional employee costs the company far less than the marginal fee an EOR would charge for the same seat.
Control becomes a real advantage at this stage too. A company running its own entity can build an in-country HR function, run its own payroll instead of routing it through a vendor, and customize benefits without having to negotiate through an EOR's standard structure. Left in place too long past this point, an EOR can turn into a ceiling on the employment relationship rather than the bridge it started as. Termination offers a similar tradeoff in reverse. In high-protection jurisdictions, a direct employment relationship gives the company more procedural control over how a termination happens, but it also means owning that procedural risk outright rather than handing it to a provider. At small headcount, an EOR's expertise in local termination law is worth more than the control a company would gain by doing it in-house. At larger headcount, building that expertise internally starts to make financial and operational sense.
None of this happens overnight. Standing up a direct entity requires registering the legal entity, building local payroll infrastructure, and often hiring local HR or legal staff, and all of that takes time to put in place while the existing EOR relationship keeps running in the background.
The compliance burden that neither model eliminates (only redistributes)
An EOR takes over the operational work of compliance, but it does not remove the company's exposure to permanent establishment risk, because that risk comes from what the worker actually does, not from who employs them on paper. If a worker performs core business activities inside their country, that can create a permanent establishment for the home company under the relevant tax treaty, which can trigger local corporate tax filings, back taxes, and transfer-pricing exposure. The EOR's employment contract offers no shield here, because permanent establishment is determined by the nature of the work being done, not by the identity of the legal employer listed on the contract.
What an EOR does absorb is substantial: payroll tax compliance, statutory benefits administration, employment contract compliance, severance calculations, and filings with local labor authorities, all high-volume, procedurally dense tasks where small errors compound fast if handled wrong. What it doesn't absorb is the client company's own corporate tax exposure, its data-residency obligations, or any IP and contractual terms that fall outside the EOR's standard template. Severance and termination procedures are where this distinction appears most sharply in practice. France, Brazil, Italy, and Mexico all have termination rules complicated enough that an unprepared company can face legal action if it lacks an EOR's specific expertise in how those calculations and procedures work.
The same redistribution logic applies on the entity side, just in the other direction. If a company owns a direct entity, it owns every compliance obligation that comes with it in-house, so it needs either local legal expertise or a payroll and compliance platform that can manage it accurately across jurisdictions. Companies operating through EOR relationships in several countries face a version of this same problem at the vendor layer: each EOR relationship comes with its own contract terms, fee structure, and compliance interface, and managing several of them at once creates coordination risk that has nothing to do with the underlying employment law.
Payroll infrastructure and the economics of both models
Whichever model you choose, EOR or direct entity, the payroll and compliance infrastructure underneath it determines how much manual work lands on finance and HR. Manual work at scale is not a fixed cost: it compounds as headcount grows, and the risk compounds along with it. Fragmented payroll environments, multiple vendors, inconsistent data formats, manual handoffs between HR systems and payroll processors, rank among the leading causes of compliance failures and make it harder to see risk across borders before it becomes a problem.
Companies running a direct entity feel this most acutely in countries with many overlapping tax jurisdictions, where the internal payroll function has to manage tax registrations, withholding calculations, filings, and notices across thousands of state and local tax jurisdictions, each with its own rules and its own deadlines. Manual HR data entry adds its own failure point: a dependent's information updated in an HRIS that doesn't automatically sync to the benefits carrier requires manual reconciliation, and that kind of gap tends to stay invisible until an audit or a claim exposes it. Platforms built around AI agents that own compliance workflows end-to-end, opening state tax accounts, resolving notices, tracking jurisdiction changes as they happen, remove the human-in-the-loop step that creates most of that lag and error.
Warp's platform is built around that premise: it monitors tax jurisdictions across the country and resolves the large majority of notices automatically before they ever reach someone on the finance or HR team, escalating only a small remainder to Warp's own compliance team. The idea behind that design is that compliance should stay invisible to the people running it, and if someone on the team is thinking about a tax notice at all, something upstream has already broken down. The legal and operational complexity of hiring directly abroad, payroll withholding across jurisdictions, country-compliant contracts, statutory benefits administration, is a major reason many high-growth companies turn to an EOR first and defer building that infrastructure. Platforms like Warp handle the payroll and compliance layer for contractors across a large number of countries, but they start from the assumption that a company has already picked its employment structure. The EOR-versus-entity decision has to come first. For a company running domestic multi-state payroll alongside international contractor payments, handling both inside one system cuts out the reconciliation work that comes from running separate tools for each, which matters more as the number of countries and states in play grows past what a manual process can track reliably.