FUTA Tax Rate, Wage Base, and Credit Reduction States
Employers in credit reduction states face triple the standard FUTA tax per employee.
FUTA’s reduced effective rate on wages up to the annual limit is a conditional baseline. This guide explains the tax, its wage base, and credit reduction exposure for 2026. Employers must distinguish established rates from pending state determinations and apply those differences across their workforce before year-end payment deadlines.
What FUTA actually is and who owes it
FUTA is a federal employer-only payroll tax that funds the administration of state unemployment insurance programs and the federal Unemployment Trust Fund. Unlike Social Security and Medicare, FUTA has no employee share. IRS coverage tests turn on wages paid in a calendar quarter or employment during enough weeks of the year, and most active employers with W-2 workers qualify.
The trust fund lends money to states that cannot meet their benefit obligations. When states fail to repay within the statutory period, employers lose part of the credit that normally reduces their federal tax.
How the statutory rate becomes a reduced effective rate — and the four conditions that keep it there
The statutory FUTA rate applies to annual wages paid to each employee up to a fixed limit. The available state unemployment tax credit reduces the effective rate when the employer qualifies in full. Wages above the annual limit are outside the FUTA calculation, and each employee’s wage-base calculation resets at the start of the calendar year.
Employers must meet four conditions to get the full credit. Employers must pay state unemployment insurance taxes in full and by the Form 940 due date. They must also pay those taxes on all the same wages subject to FUTA and operate in a state that is not subject to credit reduction. Failure to satisfy these requirements can reduce the available credit. The fourth condition is outside the employer’s direct control.
For the baseline calculation, each employee’s wages are capped at the annual limit and multiplied by the applicable rate. The amounts for all employees are then added together. Full credit supports the reduced-rate calculation, while no credit leaves the statutory rate applicable. Partial loss of credit produces a different liability.
Why the fixed wage base is structurally obsolete and what that means for employers
Congress set the FUTA wage base in 1983. It has not been adjusted since and is not indexed to inflation. As earnings rise, the base captures a shrinking share of compensation. A high-wage employee and an entry-level worker have the same maximum taxable wages once both reach the annual limit, even though their total pay is very different.
That fixed base concentrates the burden on lower-wage workforces. Seasonal, retail, and hospitality employers with high turnover face a higher effective FUTA cost as a share of payroll than employers of high-wage knowledge workers. For employees whose first paycheck reaches the limit, the annual taxable base is exhausted immediately. Higher earnings after that point add no FUTA liability.
Losing credit can raise the standard tax per employee by a large percentage even when taxable wages stay the same. No imminent legislation to adjust or index the wage base is established in the supplied material, so a pending revision cannot be treated as a planning assumption.
How a state becomes a credit reduction state and why the list is expanding in 2026
Under the federal labor department’s rules, a state must have an outstanding Social Security Act Title XII advance on January 1 of two or more consecutive years and fail to repay its advances before November 10 of the tax year. An outstanding balance alone is not enough. The department announces the final credit reduction states after that deadline.
Credit reduction is an automatic consequence of state borrowing, rather than a penalty for an employer’s own payment failure. The reduction escalates annually while the loan remains outstanding. An employer can therefore pay its state taxes as required and still owe more federal tax. The mechanism transfers the consequence of delayed state repayment to payrolls within the affected jurisdiction.
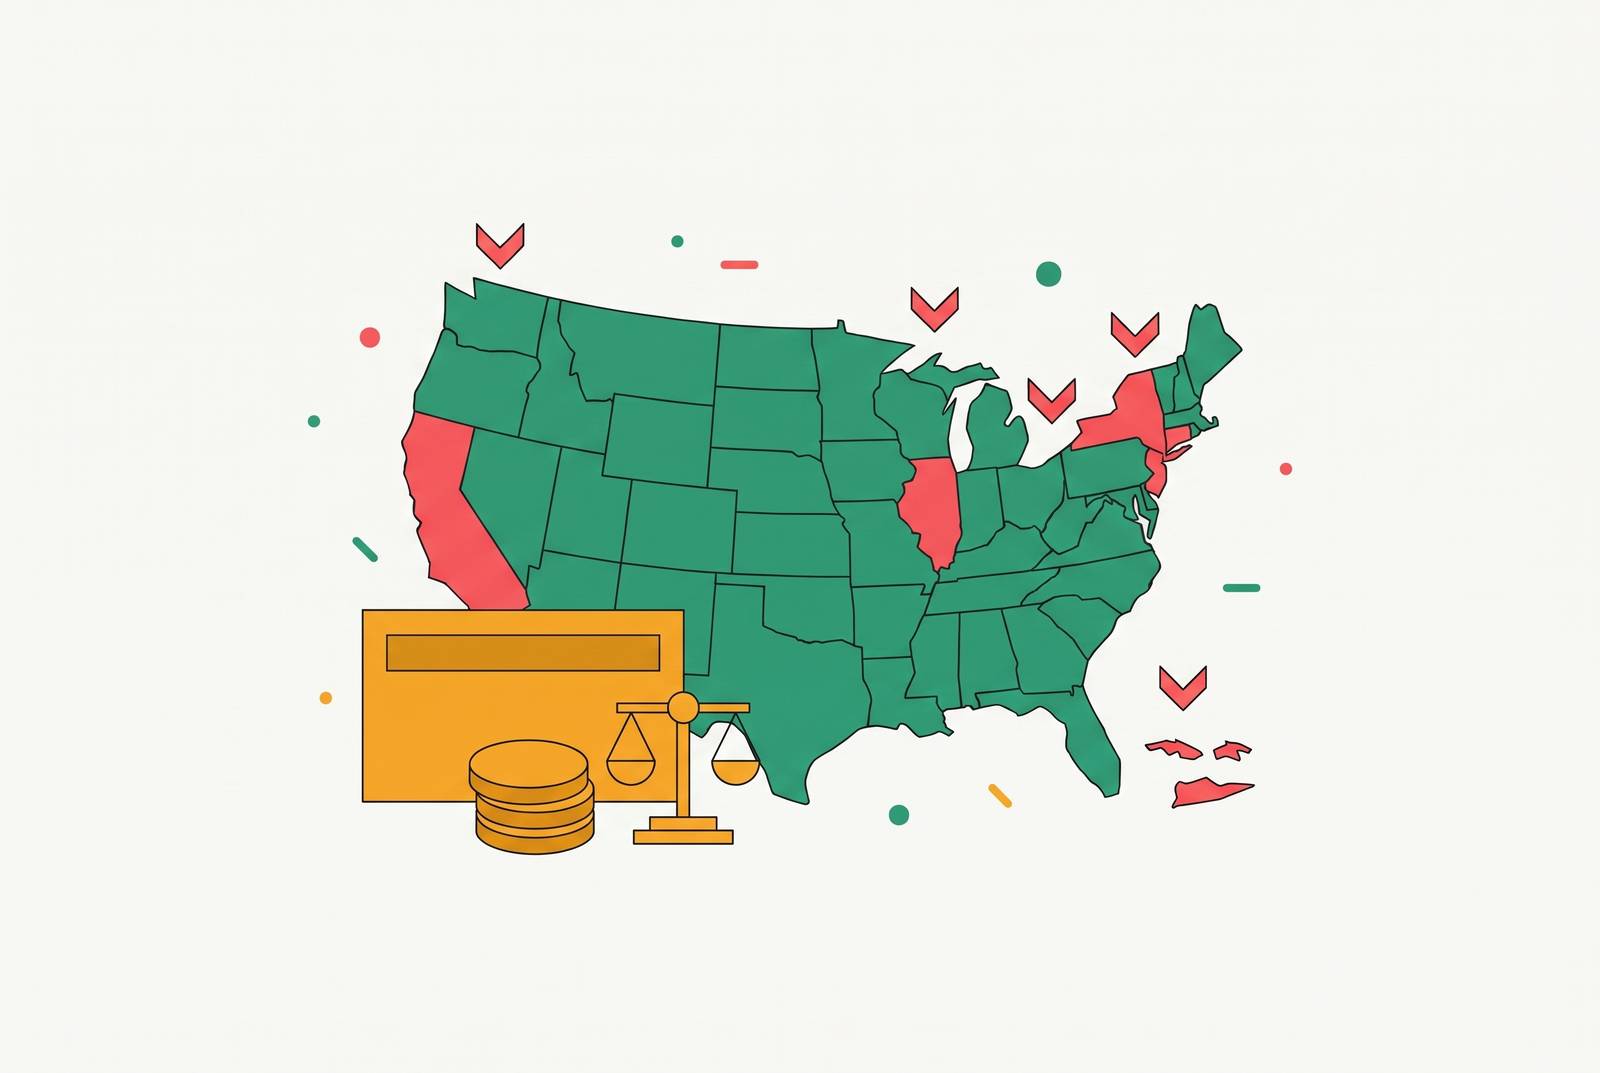
The broader 2026 exposure picture must be distinguished from a final determination. The notes describe a monitoring universe of seven states with outstanding federal loans in a Q2 picture, namely California, New York, Illinois, Connecticut, Ohio, New Jersey, and Massachusetts. Whether any state qualifies still depends on how long it has had the loan and whether it repays by November 10, so loans in more states do not by themselves establish seven credit reductions.
The confirmed 2025 credit reductions and what they cost per employee
The Federal Register notice published January 12, 2026 establishes that California and the U.S. Virgin Islands were subject to credit reductions for 2025. Neither repaid all outstanding advances before November 10, 2025. Connecticut and New York repaid before the deadline. Employers in those states therefore had no 2025 credit reduction and kept the standard reduced rate if they met the other rules for full credit.
California’s 2025 reduction made the total FUTA cost for each employee three times the standard amount. That comparison applies at the full taxable wage base. The credit adjustment changes employer cost without changing either the statutory rate or the annual wage limit. California’s reduction has grown each year that its loans have gone unpaid.
The U.S. Virgin Islands faced a much steeper reduction. Its per-employee liability approached the full statutory rate because employers had lost most of the available credit. The supplied figures do not establish an exact dollar amount for that liability. The comparison nevertheless shows how prolonged non-repayment can turn a deeply discounted federal tax into something much closer to its nominal cost.
The 2026 credit reduction outlook — what is known now and what changes after November 10
California and the U.S. Virgin Islands are on the federal labor department’s January 2026 potential-state list. Both are also on the IRS draft 2026 Schedule A. The notes’ broader loan-balance picture, including Connecticut and New York, should not be substituted for that official potential-state list.
California presents the most acute planning exposure described in the notes. Its outstanding federal loan balance is in the tens of billions, with no accelerated repayment schedule identified as of March 2026. Near-term repayment is not expected. California also faces a possible BCR add-on, which applies when benefit costs relative to taxable wages exceed a federal threshold and could raise its effective FUTA rate further.
For employers, the appropriate pre-deadline action is to review the 2025 Form 940, identify active payroll states, and compare that footprint with outstanding-loan exposure. Cost modeling should reflect workforce distribution. After November 10, 2026, the department’s final announcement establishes which states require credit reduction reporting. Affected employers must account for the additional tax on Schedule A, with the liability included in the fourth-quarter payment calculation.
How multi-state payroll turns FUTA credit reduction into a compounding liability
An employer’s headquarters does not define its entire FUTA exposure. Employers may owe more federal tax for employees who work in credit reduction states, even if the business is based elsewhere. A payroll spanning California and Ohio therefore requires separate state treatment when their applicable credit status differs.
The 2025 California outcome makes the headcount effect concrete. Each California employee who reached the wage base cost the employer three times the standard tax, while the tax for eligible employees in states without reductions stayed at the baseline. As affected headcount grows, the difference accumulates across payroll. Schedule A makes that distribution visible through state-level wages and reductions, but filing time is too late for advance funding plans.
Voluntary state contributions have a narrower role than federal credit reduction mitigation. New York allows irrevocable contributions that can lower state experience ratings and SUTA costs. California’s statutory program is prohibited under specified rate schedules and solvency conditions that remain in effect for 2026. Neither arrangement offsets federal FUTA credit reductions, so a state-tax saving cannot be treated as a substitute for the federal payment.
FUTA deposit rules, Form 940, and the penalties for getting the timing wrong
Quarterly deposits become required when the running total exceeds $500, including undeposited amounts from earlier quarters. Amounts below that trigger carry forward. The first-quarter deposit is due April 30, the second-quarter deposit July 31, and the third-quarter deposit October 31.
The fourth-quarter deadline is January 31, with Form 940. The IRS requires credit reduction liability to be included in the fourth-quarter calculation. If fourth-quarter liability plus undeposited earlier amounts is $500 or less, the employer may deposit it or pay with the return. A deadline falling on a weekend or federal holiday moves to the next business day.
Deposits are made electronically through the Electronic Federal Tax Payment System. Credit reduction amounts are reported on Schedule A of Form 940, where incomplete state reporting can understate liability. Late deposits trigger a failure-to-deposit penalty that increases with the delay. The IRS holds the employer responsible even when a third-party payroll provider handles payment, so outsourcing does not transfer penalty liability.
What FUTA exemptions actually cover and where misclassification creates hidden exposure
FUTA exemptions apply to defined organizations, workers, and payments. 501(c)(3) nonprofits, government entities, and railroad employers are exempt, and railroad unemployment is covered under the Railroad Unemployment Insurance Act. A nonprofit’s FUTA exemption does not necessarily eliminate FICA obligations. Household and agricultural employers have their own coverage tests in place of the standard general-business tests, and household employers should check whether they owe the tax under those rules.
Independent contractors are outside FUTA only when their classification is genuine under IRS rules. A 1099 label does not establish an exemption. Treating an employee as a contractor can leave unpaid FUTA that becomes back-tax liability, with penalties and interest, for the misclassification period. The exposure reflects employment that was taxable despite the employer’s original treatment.
For companies adding contractors across multiple states, the consequences extend beyond FUTA. Misclassification can also create SUTA, FICA, and state income tax withholding obligations. Separately, certain fringe benefits and employer contributions to qualified retirement plans can be exempt wages even for covered employees. Those payment-level exclusions require accurate tracking and should not be confused with a worker’s classification or an organization’s exemption.
Why FUTA compliance at scale requires systems that track rate changes without manual intervention
The wage base resets each year, a state’s credit status depends on whether it repays its federal loans, and the final decision comes shortly before year-end payments are due. Multi-state payroll adds separate wage allocations and possible BCR adjustments. Each component is manageable alone, but manual tracking becomes brittle when every component must remain aligned across a growing workforce.
Payroll settings left unchanged for the year cannot reliably keep up with that process. Connecticut and New York’s repayment before the 2025 deadline demonstrates why prior-year status is not a sufficient guide. Payroll systems must use the final decision for each state and update any earlier assumptions that no longer hold. Platforms that monitor tax jurisdictions continuously reduce dependence on manual updates between the November announcement and the fourth-quarter deadline.
Systems must connect updated state treatment to employee wages, Schedule A reporting, and the deposit calculation before payment is due. Otherwise, a team can understand FUTA correctly yet still underpay it. The employer remains accountable for closing that gap, including when a payroll provider performs the calculation and deposit.